The Kano State Government under Governor Abba Yusuf spent ₦10.36 billion on miscellaneous expenses between January and June 2026, including ₦1.21 billion on honorarium and sitting allowances and approximately ₦1.78 billion on hospitality, according to a review of the state’s second-quarter budget performance report by SaharaReporters.
The expenditure covered various items, including hospitality, publicity and advertisements, welfare packages, refreshments and meals, special days and celebrations, medical expenses and other miscellaneous costs.
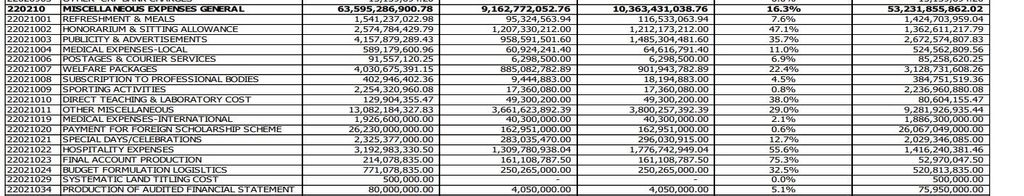
The state had allocated approximately ₦63 billion for general miscellaneous expenses in its 2026 budget. By the end of June, its year-to-date expenditure under the category had reached ₦10.36 billion, representing 16.3 per cent of the annual allocation.
The report, however, showed that the state recorded ₦9.16 billion in miscellaneous expenditure during the second quarter alone, a figure that accounts for most of the reported year-to-date spending.
The figures have raised questions about the composition of the state government’s miscellaneous expenditure and how public funds are distributed across the various budget lines.
Among the expenditure items, honorarium and sitting allowances accounted for approximately ₦1.21 billion in the first half of the year.
The Kano State Government had budgeted about ₦2.57 billion for the category in 2026. By the end of June, it had spent ₦1.212 billion, representing 47.1 per cent of the annual allocation.
The second-quarter budget performance report separately listed approximately ₦1.207 billion in expenditure under the category during the quarter, bringing the year-to-date figure to ₦1.212 billion.
Hospitality expenses also accounted for a substantial share of the state’s spending during the period.
The government allocated approximately ₦3.19 billion for hospitality expenses in its 2026 budget but had spent about ₦1.78 billion by the end of June, representing 55.6 per cent of the annual provision.
The report showed that ₦1.31 billion was recorded under hospitality expenses in the second quarter alone.
Publicity and advertisements constituted another major expenditure item, with the state allocating approximately ₦4.16 billion for the category in the 2026 fiscal year.
By the end of June, expenditure on publicity and advertisements had reached ₦1.49 billion, representing 35.7 per cent of the annual allocation.
The government also recorded approximately ₦901.94 million in expenditure on welfare packages during the first six months of the year, against an annual budget of ₦4.03 billion.
Spending on refreshments and meals stood at ₦116.53 million by the end of June. The amount represented 7.6 per cent of the ₦1.54 billion allocated for the category in the 2026 budget.
The budget performance report further showed that the state recorded ₦3.80 billion under the separate category of other miscellaneous expenses during the period.
The government had allocated approximately ₦13.08 billion for the category for the full year, meaning the expenditure recorded by the end of June represented about 29 per cent of the annual provision.
Other items listed in the report included special days and celebrations, local medical expenses and international medical expenses.
The state recorded ₦296.03 million for special days and celebrations during the first six months of 2026. It also spent ₦64.62 million on local medical expenses and ₦40.30 million on international medical expenses.
The figures form part of the broader miscellaneous expenses heading, which comprises several distinct expenditure categories rather than a single spending item.
Meanwhile, the Kano State Government spent ₦162.95 million under its foreign scholarship scheme during the first half of the year.
The amount represented just 0.6 per cent of the ₦26.23 billion allocated to the programme for the entire 2026 fiscal year.
The figures highlight differences in the pace of expenditure across the state’s budget lines, with hospitality and honorarium and sitting allowances accounting for substantial portions of their respective annual allocations by the end of June.
However, the budget performance figures alone do not establish whether the expenditure was unlawful or improperly incurred. Determining how the funds were used would require further details on the individual payments, their purposes and the supporting financial records.